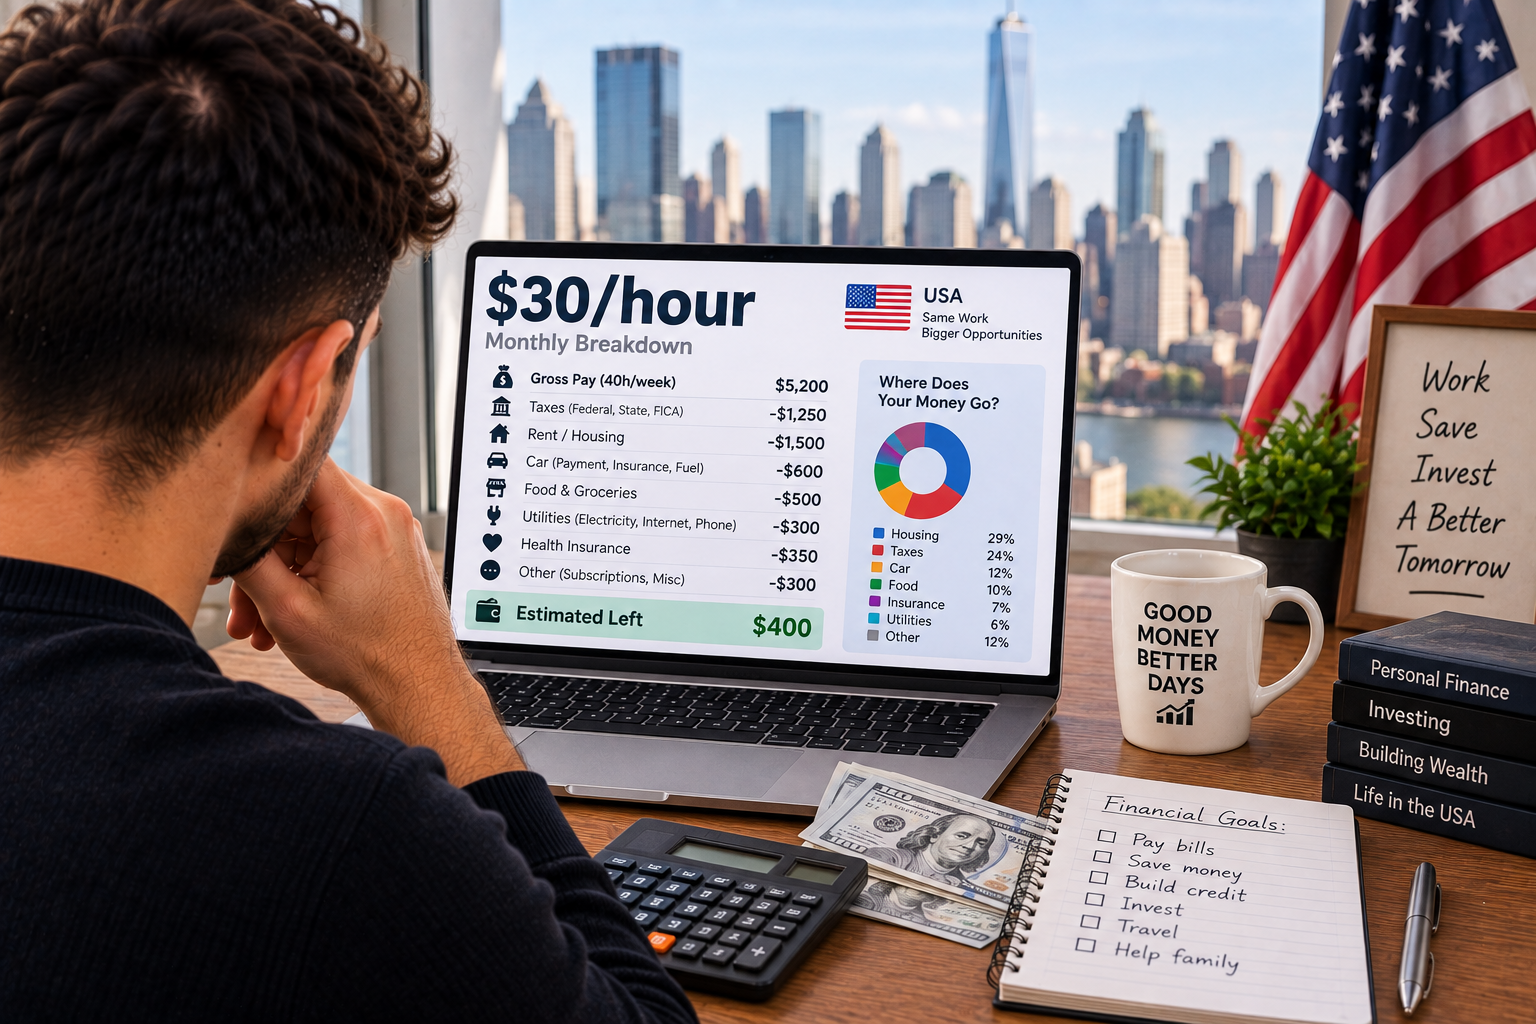
Albanians Making $30 an Hour in America: How Much Money Is Really Left at the End of the Month?
$30 an hour sounds like a good salary.
But how much money does someone earning $30 per hour in the United States actually have available at the end of the month?
For Albanians living and working in America, the answer can be very different depending on the state, tax filing status, health insurance, retirement contributions, housing costs, car payments and family situation.
A worker earning $30 per hour does not take home $30 for every hour worked.
Federal income tax, Social Security, Medicare and potentially state and local taxes can come out before the paycheck reaches your bank account.
Then come rent or mortgage, groceries, insurance, transportation and other monthly bills.
Let’s break down the numbers.
$30 an Hour: How Much Is That Per Year?
Let’s assume you work:
40 hours per week
at:
$30 per hour
Your gross weekly income would be:
$30 × 40 = $1,200
Across 52 weeks:
$1,200 × 52 = $62,400 per year
So a full-time worker earning $30 per hour could have approximately:
$62,400 gross annual income
before taxes and other deductions.
The average gross monthly equivalent is:
$62,400 ÷ 12 = $5,200 per month
If you’re paid every two weeks, a typical gross paycheck for 80 hours would be:
$2,400
Remember that months don’t all contain exactly four weeks, so multiplying $1,200 by four gives only $4,800 and understates the average monthly equivalent.
Gross Pay Is Not Take-Home Pay
Seeing:
$62,400 per year
or:
$5,200 per month
doesn’t mean that amount is available to spend.
Several deductions can reduce your paycheck.
The major ones can include:
Federal income tax
Social Security
Medicare
State income tax, where applicable
Local income taxes, where applicable
Health insurance
401(k) or other workplace benefits
The exact amount depends heavily on the individual.
Social Security and Medicare
These two payroll taxes are relatively straightforward for a typical W-2 employee.
For 2026, employees generally pay 6.2% for Social Security on covered wages up to the annual wage base and 1.45% for Medicare.
At $62,400 per year:
Social Security
$62,400 × 6.2% = $3,868.80 per year
That’s approximately:
$322.40 per month
Medicare
$62,400 × 1.45% = $904.80 per year
That’s approximately:
$75.40 per month
Combined employee Social Security and Medicare:
$4,773.60 per year
or an average of approximately:
$397.80 per month
So before considering federal income tax, state tax, health insurance or retirement contributions, almost $400 per month of this hypothetical worker’s gross income is already accounted for by these two payroll taxes.
What About Federal Income Tax?
Federal income tax isn’t simply:
Salary × one tax percentage.
The U.S. uses marginal tax brackets.
For tax year 2026, the standard deduction is $16,100 for a single filer, $32,200 for married couples filing jointly, and $24,150 for heads of household.
For a simple hypothetical single taxpayer earning $62,400 entirely as ordinary W-2 wages, with no dependents or other adjustments, taxable income after the $16,100 standard deduction could be approximately:
$62,400 − $16,100 = $46,300
Under the 2026 federal brackets for single filers, the first $12,400 of taxable income is in the 10% bracket, with the next portion up to $50,400 in the 12% bracket.
A simplified calculation would therefore be approximately:
10% of first $12,400 = $1,240
12% of remaining $33,900 = $4,068
Estimated federal income tax:
$5,308 per year
or approximately:
$442 per month
This is an illustrative tax calculation, not a prediction of someone’s paycheck or final tax bill. Credits, pre-tax deductions, dependents, filing status and many other factors can materially change the result.
A Simplified Take-Home Example
Let’s use the hypothetical single employee above.
Annual gross income:
$62,400
Minus estimated federal income tax:
−$5,308
Minus Social Security:
−$3,868.80
Minus Medicare:
−$904.80
Approximate amount remaining:
$52,318
Average monthly equivalent:
About $4,360
But we’re still not finished.
This example does not yet subtract state or local income tax, health-insurance premiums, 401(k) contributions or other payroll deductions.
So seeing approximately $4,360 here does not mean every $30/hour worker will receive that amount in their bank account.
Your State Can Make a Big Difference
Where you live matters.
Two Albanian workers can both earn:
$30/hour
and have different take-home pay because state and local tax systems vary.
Beyond taxes, their living costs can be completely different.
A worker in one part of the country might pay:
$1,200 rent
while another household might pay:
$2,500 or more
for housing.
Car insurance, property taxes, childcare, health costs and groceries can also vary significantly by location.
This is why asking:
“Is $30/hour a good salary in America?”
doesn’t have one universal answer.
You need to know both:
Take-home pay
and
Cost of living.
Health Insurance Can Reduce the Paycheck Further
Many Americans receive health coverage through an employer, but employees may still pay part of the premium.
Suppose your share is hypothetically:
$250 per month
Your available income falls again.
And insurance premiums aren’t necessarily your only healthcare expense.
Depending on the plan, you may also encounter:
Deductibles
Copays
Coinsurance
Prescription costs
Out-of-pocket maximums
Dental insurance
Vision insurance
For a family plan, employee contributions can be substantially different from individual coverage.
Always check your actual pay stub and benefits documents.
What About a 401(k)?
Suppose you contribute:
5% of your $62,400 salary
to a workplace 401(k).
That’s:
$3,120 per year
or an average of:
$260 per month
A traditional 401(k) contribution can generally reduce current federal taxable income, so its effect on take-home pay isn’t simply identical to subtracting $260 after tax.
But from a cash-flow perspective, it still means part of your paycheck is being directed toward retirement instead of your checking account.
That money hasn’t necessarily “disappeared.”
You’re saving it for retirement.
If your employer offers a match, understand the plan before deciding whether to participate.
Now Comes the Real Question: What Is Left After Living Expenses?
Suppose that after taxes and payroll deductions, our hypothetical worker has around:
$4,000 per month
available in take-home pay.
Now let’s build a hypothetical monthly budget.
Housing: $1,500
Utilities: $220
Groceries: $550
Car payment: $400
Car insurance: $180
Gas: $180
Phone/internet: $130
Healthcare/out-of-pocket: $120
Subscriptions/entertainment: $120
Other household/personal expenses: $300
Total:
$3,700
Take-home:
$4,000
Money remaining:
$300 per month
That’s the number that matters.
A salary can look relatively strong on paper while leaving little room after fixed expenses.
Your Car Could Be Taking More Than You Think
Many people budget only for the monthly car payment.
For example:
Car payment = $450
But your actual transportation costs could look more like:
Car payment: $450
Insurance: $190
Gas: $200
Maintenance reserve: $75
Parking/tolls: $60
Total:
$975 per month
That’s nearly:
$12,000 per year
in this hypothetical example.
A household earning $62,400 annually could therefore be directing a significant portion of its take-home income toward transportation.
Before upgrading your vehicle, calculate the entire cost—not just the monthly finance payment.
Housing Can Change Everything
Consider two people earning exactly $30 per hour.
Worker A
Take-home: $4,000
Housing: $1,300
Money after housing:
$2,700
Worker B
Take-home: $4,000
Housing: $2,300
Money after housing:
$1,700
Same wage.
Same gross annual salary.
But Worker A has:
$1,000 more per month
available after housing.
Over one year:
$12,000 difference.
This is why salary alone doesn’t tell you someone’s financial situation.
What If You Work Overtime?
For many covered, nonexempt workers, federal law generally requires overtime of at least 1.5 times the regular rate for hours worked over 40 in a workweek. Exemptions and special rules can apply.
At $30 per hour, 1.5 times the regular rate would be:
$45 per hour
Suppose an eligible worker works five overtime hours:
5 × $45 = $225 additional gross pay per week
If that happened every week for four weeks, that would be:
$900 additional gross pay
But don’t confuse gross overtime with the amount you’ll actually keep.
Taxes and other applicable deductions can still affect the paycheck.
Also, federal law doesn’t automatically require overtime merely because you work on Saturday, Sunday or a holiday; for covered nonexempt workers, the general federal overtime rule is based on working over 40 hours in a workweek.
What If Two People in the Household Earn $30/Hour?
This changes the picture dramatically.
If two spouses each earn:
$62,400 per year
their combined gross employment income would be:
$124,800 per year
Average gross monthly household income:
$10,400
But you cannot simply double the single-worker tax example.
Married filing status, deductions, benefits, children, childcare costs and other factors can produce a different tax and household-budget outcome.
For 2026, the standard deduction for married couples filing jointly is $32,200.
A two-income household may have much more financial flexibility, but it can also face higher childcare, commuting, healthcare and other expenses.
Don’t Forget Irregular Expenses
A monthly budget often looks good because people forget expenses that don’t happen every month.
For example:
Car repairs
Medical bills
Car registration
Home repairs
Insurance deductibles
Birthdays
Christmas
Flights to Albania or Kosovo
Vacations
School expenses
Clothing
Furniture
Emergency travel
Suppose these expenses average:
$4,800 per year
That’s effectively:
$400 per month
even if you don’t receive a $400 bill every month.
A realistic budget should account for irregular expenses too.
$300 Left Over Is Not Necessarily $300 to Spend
Suppose everything is paid and you have:
$300 remaining.
You could spend it.
But you may also need to build:
Emergency savings
Retirement savings
A home down payment
A car-repair fund
Travel savings
Debt repayment
Other long-term savings
Having $300 “left over” isn’t the same as having $300 you can safely spend without considering future obligations.
Look at Your Pay Stub
If you earn $30/hour, don’t estimate your finances from your hourly rate alone.
Open your pay stub.
Check:
Gross pay
Hours worked
Overtime
Federal income-tax withholding
Social Security
Medicare
State/local withholding where applicable
Health insurance
401(k)
Other deductions
Net pay
Then open your bank statement.
Calculate:
Net income − actual monthly expenses = money really left.
That gives you a much better answer than simply multiplying $30 by 40 hours.
The Bottom Line
An Albanian worker in America earning $30 per hour and working 40 hours per week could earn approximately:
$1,200 gross per week
$5,200 average gross per month
$62,400 gross per year
But that is not take-home pay.
For 2026, a typical employee is subject to Social Security withholding of 6.2% and Medicare withholding of 1.45%, while federal income tax depends on taxable income and filing circumstances.
State taxes, health insurance, retirement contributions and other deductions can reduce the paycheck further.
Then come the expenses that determine how wealthy—or stretched—you actually feel:
Housing.
Car.
Insurance.
Food.
Utilities.
Healthcare.
Debt.
Family expenses.
So instead of asking only:
“I make $30 an hour—is that good?”
Ask:
“After taxes and all my expenses, how much can I save every month?”
Because earning $62,400 per year and saving $100 per month is a very different financial situation from earning the same salary and consistently saving $1,000.
Your hourly wage tells you what your employer pays you.
Your monthly cash flow tells you what that salary actually does for your life.
Disclaimer: This article is for general educational purposes only and does not constitute personalised tax, financial, investment, employment or legal advice. Tax liability and take-home pay depend on filing status, state and local rules, deductions, credits, benefits and individual circumstances. The calculations above are simplified hypothetical examples based on 2026 federal rules and should not be treated as a personal tax estimate.