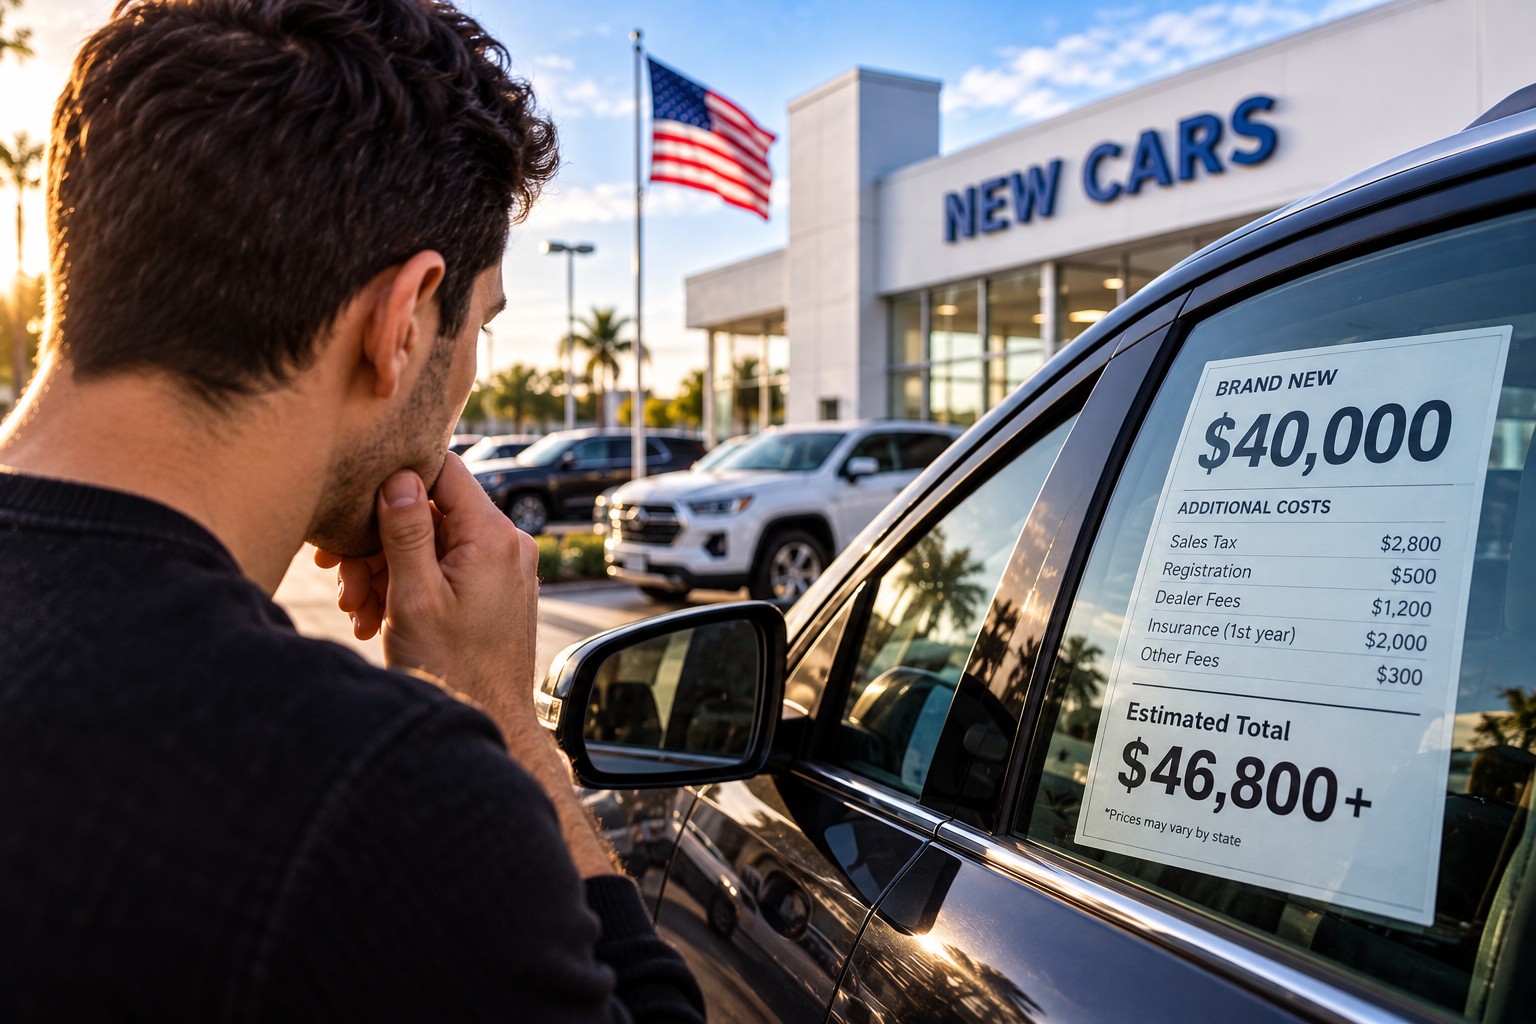
Albanians in America: A $40,000 Car Could Cost You Much More Than the Price at the Dealership
You walk into a dealership in America and see the car you want:
Price: $40,000
You might naturally think:
“This car costs $40,000.”
But that number may only be the beginning.
If you’re financing the vehicle, the amount that eventually leaves your household budget can be significantly higher once you include:
Interest
Taxes and registration
Dealer fees
Optional add-ons
Auto insurance
Gas
Maintenance and repairs
Tires
and other ownership expenses.
For Albanians living in America, especially families considering a newer or more expensive vehicle, there is one important rule:
Don’t ask only how much the car costs today. Ask how much it could cost you to buy, finance and own it.
The Consumer Financial Protection Bureau explains that the advertised vehicle price is only part of the total cost. Financing, add-ons, insurance, maintenance and fuel can all increase what owning the vehicle ultimately costs.
Start With the $40,000 Price
Let’s create a hypothetical example.
Vehicle price:
$40,000
Down payment:
$5,000
At first glance, you might think you need to finance:
$35,000
But the final amount financed could be higher once applicable taxes, fees and optional products are included.
For illustration, suppose the transaction eventually looks like this:
Vehicle: $40,000
Taxes/title/registration and other transaction costs: $3,000
Optional products: $2,000
Total before down payment:
$45,000
Down payment:
-$5,000
Amount financed:
$40,000
You put $5,000 down.
Yet you’re still financing approximately:
$40,000.
This is why the price on the windshield doesn’t necessarily equal the amount appearing in your loan agreement.
CFPB notes that taxes, government fees, dealer fees and optional add-ons can all affect the amount financed and total purchase cost.
Then Comes the Interest
Now imagine financing:
$40,000
for:
72 months
at a hypothetical:
8% interest rate.
The approximate monthly payment would be:
$701
Over 72 months, total loan payments would be approximately:
$50,500
Approximate interest:
$10,500
Remember that you already paid:
$5,000 down.
So your total cash outlay toward acquiring and financing the vehicle would already be around:
$55,500
under this simplified example.
And we haven’t included six years of insurance, fuel or maintenance.
The CFPB emphasizes that longer loan terms can reduce the monthly payment while increasing total interest costs.
The Interest Rate Can Change the Cost by Thousands
Let’s keep the amount financed at:
$40,000
and the term at:
72 months.
At 5%
Approximate monthly payment:
$644
Approximate total interest:
$6,400
At 8%
Approximate monthly payment:
$701
Approximate total interest:
$10,500
At 12%
Approximate monthly payment:
$782
Approximate total interest:
$16,300
These are simplified examples.
But notice the difference.
Same car.
Same amount borrowed.
Same 72-month term.
Approximate interest difference between 5% and 12%:
Nearly $10,000.
That’s why negotiating only the vehicle price isn’t enough.
You also need to understand your financing.
Interest Rate and APR Aren’t Exactly the Same
When comparing loans, look at:
Interest rate
and:
APR
The CFPB explains that the interest rate represents the cost of borrowing the principal, while APR is a broader measure that includes the interest rate plus certain additional loan fees.
Before you’re legally obligated on an auto loan, federal Truth in Lending rules require disclosures including important information such as the APR, finance charge and payment terms.
Don’t sign simply because the salesperson says:
“Your payment is only $699.”
Ask:
What’s the APR?
What’s the amount financed?
What’s the finance charge?
How many payments?
What’s the total of payments?
Those numbers tell you much more.
The “Affordable Monthly Payment” Trap
Imagine you tell the dealership:
“I don’t want to pay more than $650 per month.”
That can become the wrong starting point.
A payment can be lowered by stretching the loan over more months.
Suppose you finance:
$40,000 at 7%.
A shorter loan means a higher monthly payment but less time paying interest.
A longer loan means a lower payment but potentially more total interest.
CFPB provides exactly this warning: focusing on the monthly payment alone can hide the true cost of the loan, and longer terms generally increase total interest.
Instead of asking:
“Can you get me under $650?”
ask:
“What’s the total amount I’ll pay for this vehicle?”
A 72- or 84-Month Loan Can Make an Expensive Car Look Affordable
This is how buyers can end up purchasing more car than they originally planned.
Suppose:
60-month payment: $790
72-month payment: $690
84-month payment: $610
The 84-month option looks easier.
But now you’re committing yourself to payments for:
Seven years.
The vehicle will continue aging during those seven years.
You could eventually be making:
Car payment + repair payments
at the same time.
Longer loans also increase the period during which you could potentially owe more than the vehicle is worth—a situation known as:
Negative equity.
CFPB specifically warns that longer auto loans can increase this risk.
What Is Negative Equity?
Suppose after some time:
Remaining auto loan:
$32,000
Vehicle value:
$26,000
Difference:
$6,000
You’re:
$6,000 upside down.
If you want to sell or trade the car, that debt doesn’t magically disappear.
A dealership may offer to roll the negative equity into your next loan.
But then you could begin financing your next car while still paying debt associated with the old one.
CFPB warns that rolling negative equity into a new auto loan increases the amount financed and the total cost of the new loan.
Taxes and Registration Can Add Thousands
A $40,000 vehicle doesn’t necessarily leave the dealership for exactly $40,000.
Depending on your state and transaction, you may face:
Sales tax
Title fees
Registration fees
Other government charges
The exact amount varies substantially across the United States.
For example, if applicable taxes and government fees hypothetically add:
$3,000
your $40,000 purchase has already become:
$43,000
before financing costs.
CFPB notes that taxes, title and registration fees established by state and local governments are generally not negotiable, unlike some dealer charges.
Dealer Add-Ons Can Increase the Loan
Then you reach the finance office.
You may be offered:
Extended warranty or service contract
GAP coverage
Tire-and-wheel protection
Credit insurance
Paint protection
Alarm systems
Other products
Some may provide value depending on your situation.
But understand whether they’re:
Required or optional.
CFPB states that products such as extended warranties, GAP insurance and credit insurance are generally optional rather than automatically required to obtain an auto loan.
Now imagine adding:
Extended warranty: $2,500
GAP product: $900
Other protection: $600
Total:
$4,000
If you finance those products instead of paying cash, you’re not only paying:
$4,000.
You’re potentially paying interest on them too.
A $2,500 Add-On Can Cost More Than $2,500
Suppose:
Optional product: $2,500
and it gets added to a:
72-month loan at 8%.
The extra financed amount could add roughly:
$44 per month.
Over 72 months:
Around $3,150
in total payments attributable to that financed amount.
So the:
$2,500 product
could ultimately cost roughly:
$650 more
because it was financed.
This is why every optional product deserves the same question:
“What’s the total cost if I finance this?”
Insurance Can Be a Major Expense
Now the vehicle is yours.
The loan payment is:
$700/month.
But you still need insurance.
Suppose your premium is:
$220/month
That’s:
$2,640/year.
Across six years, assuming the price never changed:
$15,840
Of course, real insurance premiums can rise or fall over time.
Your cost depends on factors including the driver, vehicle, location, coverage, deductible, insurer and other underwriting factors.
CFPB specifically advises consumers to include insurance when calculating what they can afford to spend on a vehicle.
Get an insurance quote before buying the car.
Don’t discover after signing that the vehicle costs hundreds more per month to insure than you expected.
Fuel Can Add Another Five-Figure Cost
Suppose you spend:
$200/month
on fuel.
Annual cost:
$2,400
Six years:
$14,400
Now combine only:
Insurance: $15,840
Fuel: $14,400
That’s already:
$30,240
over six years under our hypothetical assumptions.
And those costs exist separately from the vehicle purchase and financing.
Maintenance Doesn’t Stop Because the Car Is New
New vehicles may require less repair work initially.
But they still need ongoing maintenance.
Depending on the vehicle and usage, costs can include:
Oil and filters
Tires
Brakes
Battery
Fluids
Alignment
Scheduled servicing
Wear items
Unexpected repairs
Suppose you reserve:
$100/month
for maintenance, tires and future repairs.
That’s:
$1,200/year
or:
$7,200 over six years.
The exact amount could be much lower or much higher.
But pretending maintenance costs:
$0
isn’t a realistic long-term budget.
CFPB specifically lists maintenance and repairs among the costs consumers should consider when evaluating total vehicle affordability.
Don’t Forget Parking and Tolls
For some households:
$0
For others:
Hundreds per month.
Suppose you spend:
Parking: $100/month
Tolls: $75/month
Combined:
$175/month
Annual:
$2,100
Six years:
$12,600
This is particularly relevant for commuters and people living in expensive metropolitan areas.
Now Calculate the Real Monthly Car Budget
Imagine this hypothetical $40,000 vehicle:
Loan payment: $700
Insurance: $220
Fuel: $200
Maintenance reserve: $100
Parking/tolls: $100
Total:
$1,320/month
That’s:
$15,840 per year
The car payment itself represents only:
$700
of the:
$1,320
monthly transportation budget.
This is why saying:
“I can afford the $700 payment”
doesn’t necessarily mean:
“I can comfortably afford the car.”
What If You Have Two Cars?
Now imagine a married couple needs two vehicles.
Car 1 total monthly cost:
$1,200
Car 2 total monthly cost:
$900
Combined:
$2,100/month
Annual:
$25,200
A household earning a good salary can still feel financially stretched if a large portion of its income is tied to vehicles.
This is particularly important when the household also has:
Mortgage or rent
Credit cards
Children
Health insurance
Student loans
Retirement contributions
Groceries
Travel
Emergency savings
The Car Also Loses Value
There’s another cost that doesn’t appear as a monthly bill:
Depreciation.
A vehicle is generally a depreciating asset.
Suppose you spend:
$40,000
and several years later the vehicle is worth:
$22,000.
You haven’t received an $18,000 invoice.
But economically, the asset has lost:
$18,000 in value.
Actual resale values vary significantly by make, model, mileage, age, condition and market conditions.
This matters especially if you’re financing for a long period.
The loan balance and vehicle value don’t necessarily fall at the same speed.
That’s one reason negative equity can develop.
A $40,000 Car Could Consume $80,000+ Over Time
Let’s combine a hypothetical six-year ownership scenario.
Vehicle transaction before financing: $43,000
Financing cost: $10,000
Insurance over six years: $15,800
Fuel: $14,400
Maintenance/tires/repairs: $7,200
Registration and miscellaneous ownership costs: $2,000
Combined cash outflow:
Approximately $92,400
This is intentionally a broad hypothetical example.
It does not mean every $40,000 vehicle will cost $92,400.
Some owners will spend far less.
Some may spend more.
Insurance, fuel, financing, taxes, maintenance and ownership duration vary dramatically.
But it demonstrates why:
$40,000 purchase price
and:
Total cost of ownership
are completely different numbers.
What About a $5,000 Down Payment?
Another mistake is forgetting the down payment when calculating what the car cost.
Suppose you say:
“My payments were $700 for 72 months.”
That’s:
$50,400
But if you originally paid:
$5,000 down
your acquisition-related cash outlay was already:
$55,400
before considering insurance and operating expenses.
Your down payment is still money you spent.
It doesn’t disappear from the calculation simply because it wasn’t financed.
Your Trade-In Is Money Too
Suppose you trade in your old car for:
$8,000
and put another:
$4,000 cash down.
You might think:
“I only put $4,000 down.”
Economically, you contributed:
$12,000 of value
toward the transaction.
The old vehicle wasn’t free.
It was an asset you gave up.
When comparing deals, keep:
Vehicle price
Trade-in value
and:
Financing
separate.
Otherwise, it’s easy for a transaction to look better than it really is.
Don’t Negotiate Only the Payment
Imagine:
Dealer: “How much do you want to pay monthly?”
You: “Maximum $600.”
The dealer might be able to reach $600 by changing:
Loan term
Down payment
Amount financed
Add-ons
Other financing details
But you still don’t know whether you’re getting a good deal.
CFPB recommends negotiating and comparing the total cost, not just the monthly payment.
Before signing, know:
Vehicle selling price
Amount financed
APR
Finance charge
Loan term
Monthly payment
Total of payments
Down payment
Trade-in value
Add-ons
That’s the complete picture.
Shop for Financing Before Shopping for the Car
You don’t necessarily have to accept the first financing offer presented at the dealership.
Consider checking with:
Banks
Credit unions
Other auto lenders
before finalizing the purchase.
CFPB says comparing multiple lender quotes and getting preapproved before visiting the dealership can help consumers negotiate financing.
Suppose:
Dealer offer: 10% APR
Credit union offer: 7% APR
The monthly difference may not look enormous.
But across a large loan and several years, the total difference can be thousands of dollars.
Credit Score Can Matter
Two people can buy identical:
$40,000 vehicles
on the same day.
One may receive a lower interest rate.
The other may receive a substantially higher rate.
CFPB says credit reports and scores are among the important factors lenders use when determining auto-loan pricing; lower scores generally increase the likelihood of receiving higher rates.
Before buying an expensive car, check your credit.
A stronger financial profile can potentially reduce borrowing costs.
Don’t Let the Car Destroy Your Other Goals
Suppose household take-home income is:
$6,500/month.
Total car cost:
$1,300/month
Mortgage/rent:
$2,200
Groceries:
$900
Utilities/phone/internet:
$600
Health and other insurance:
$500
Debt:
$400
Total:
$5,900
Remaining:
$600
That $600 still needs to cover:
Savings
Emergencies
Travel
Clothing
Children
Home repairs
Entertainment
Unexpected expenses
The household may technically make the car payment every month.
But the vehicle could still make the overall budget uncomfortable.
The “Can I Buy It?” Test
Before buying a $40,000 car, calculate three numbers.
1. Upfront Cost
How much cash are you using for:
Down payment
Taxes
Fees
Trade-in value
2. Monthly Cost
Calculate:
Loan payment
Insurance
Fuel
Parking/tolls
Maintenance reserve
3. Total Long-Term Cost
Estimate:
Total loan payments
Down payment
Insurance
Fuel
Maintenance
Registration
Other ownership expenses
Then ask:
“If I saw the total number today, would I still buy this car?”
That’s a much better affordability test than:
“Can I make the monthly payment?”
Seven Things to Check Before Signing
Before buying a $40,000 vehicle in America, check:
1. The out-the-door price — not only the advertised price.
2. APR and interest rate — understand the cost of financing.
3. Loan term — lower payments over more years can mean more interest.
4. Optional add-ons — know exactly what you’re buying and financing.
5. Insurance quote — get it before signing.
6. Total operating cost — fuel, maintenance, registration, parking and repairs matter.
7. Total of payments — know how much the financing agreement can ultimately cost.
Under Truth in Lending rules, lenders must disclose important auto-loan terms such as APR and finance charges before you’re obligated on the loan.
Read those numbers.
The Bottom Line
A car with a:
$40,000 price tag
can ultimately cost much more than:
$40,000.
You may also pay:
Taxes and fees
Loan interest
Optional products
Insurance
Fuel
Maintenance
Repairs
Registration
Parking and tolls
And the vehicle will generally lose value over time.
CFPB’s guidance is straightforward: when comparing auto financing, don’t focus only on the monthly payment. Look at the amount financed, APR, loan term and total cost.
For Albanians living in America, the smartest question before buying a $40,000 vehicle isn’t:
“Can I afford $700 per month?”
It’s:
“How much will this car take out of my pocket from the day I buy it until the day I sell it?”
Because the number on the dealership window tells you the price of the vehicle.
It doesn’t tell you the full cost of owning it.
Disclaimer: This article is for general educational purposes only and does not constitute personalised financial, auto-loan, credit, tax, insurance or legal advice. Interest rates, taxes, insurance premiums, fees, maintenance costs and vehicle values vary substantially. All dollar examples are hypothetical and are not estimates for a specific borrower or vehicle.