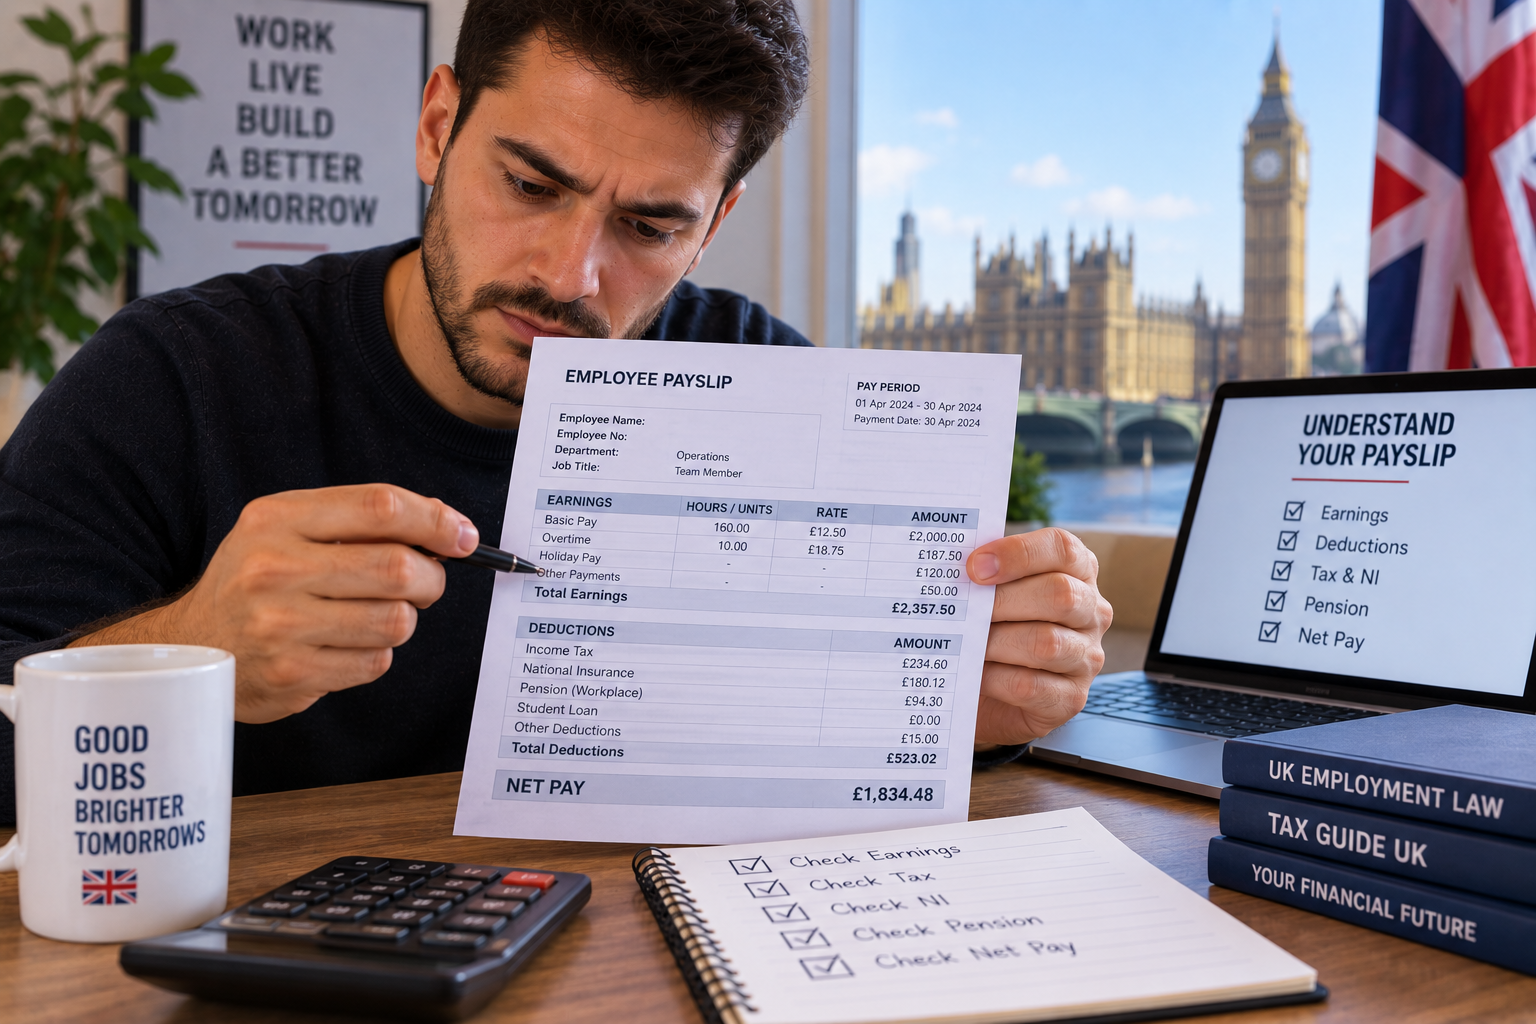
# Working in England? How to Read Your Payslip From Start to Finish
If you work in England, your payslip is one of the most important financial documents you receive.
Yet many employees look at only one number:
**The amount that reaches their bank account.**
That can be a mistake.
Your payslip can tell you how much you earned before deductions, how much Income Tax and National Insurance was taken, what you contributed to your workplace pension, whether other deductions were made, and how much money you actually took home.
For Albanians working in England, understanding these numbers can be especially useful if you’re new to the UK payroll system.
Here’s how to read your payslip from start to finish.
## 1. Start With Your Personal and Employment Information
The top section of a payslip commonly contains basic information identifying you and the payroll period.
Depending on your employer and payroll software, you may see information such as:
Your name
Employee or payroll number
National Insurance number
Tax code
Pay date
Pay period
Department or job information
Not every payslip looks identical.
Employers use different payroll systems, so the location and terminology can vary.
However, make sure the payslip actually belongs to you and covers the correct pay period before examining the numbers.
## 2. Find Your Gross Pay
One of the first major numbers to understand is **gross pay**.
Gross pay is what you’ve earned before deductions are taken.
For example, suppose you earn:
**£15 per hour**
and work:
**160 paid hours**
A simple calculation would be:
**£15 × 160 = £2,400**
So your basic gross earnings would be £2,400 before considering other payments or deductions.
However, gross pay can contain more than your normal salary.
Depending on your job, you might also see:
Basic pay
Overtime
Bonus
Commission
Holiday pay
Shift premium
Other taxable payments
If you worked overtime, check whether those hours and the applicable rate appear as expected.
Don’t automatically assume the payroll calculation is correct simply because you received a payment.
## 3. Check the Number of Hours
If your pay varies according to the number of hours you work, your payslip should provide information about the hours for which you’re being paid.
This is particularly important for hourly workers.
Imagine you expected payment for 170 hours but the payslip shows only 155.
Even if everything else is calculated correctly, the missing hours could significantly affect your final pay.
Compare your payslip with your own records where appropriate.
Check:
Normal hours
Overtime hours
Night shifts
Weekend work
Holiday hours
Other paid time
Keeping your own record of hours can make it much easier to identify a possible payroll discrepancy.
## 4. Understand Your Tax Code
Your **tax code** is one of the most important pieces of information on a UK payslip.
HM Revenue & Customs, or HMRC, uses tax codes as part of the PAYE system to tell employers how Income Tax should be calculated for an employee’s circumstances.
A commonly seen tax code is **1257L**, although your own code may be different.
Don’t assume everyone should have the same tax code.
Your code can depend on your circumstances.
You may also see codes or markers such as:
BR
0T
K codes
W1
M1
X
These can mean very different things.
For example, certain codes may appear when you have more than one job, your Personal Allowance has been used elsewhere, HMRC needs additional information, or an emergency basis is being used.
If your tax code suddenly changes, investigate why.
A different tax code can change how much Income Tax is deducted from your wages.
## 5. What Is PAYE Income Tax?
PAYE stands for:
**Pay As You Earn.**
Under PAYE, your employer generally calculates and deducts Income Tax from your wages before paying you and reports/payments are handled through the payroll system.
So instead of receiving all your gross salary and then manually paying the normal payroll tax amount each month, employees generally receive pay after the relevant PAYE deduction has already been made.
Your payslip may show this deduction as something like:
PAYE
Tax
Income Tax
The amount can depend on your taxable pay, tax code and circumstances.
Don’t simply compare your Income Tax deduction with a coworker’s.
Two people earning similar salaries can have different tax situations.
## 6. Understand Your Personal Allowance
The **Personal Allowance** is an important part of the UK Income Tax system.
For many taxpayers, a certain amount of income can be received before Income Tax becomes due.
But your individual allowance and tax code can be affected by your circumstances.
This is one reason understanding your tax code matters.
If you’re unsure whether your tax code reflects your circumstances, check it rather than guessing based on what appears on someone else’s payslip.
## 7. What Is National Insurance?
Another major deduction you may see is:
**National Insurance**
or
**NI**
For employees, Class 1 National Insurance contributions can be deducted through payroll when earnings meet the applicable thresholds.
National Insurance is separate from Income Tax.
That means your payslip could show both:
**PAYE Income Tax**
and
**National Insurance**
as separate deductions.
The amount of National Insurance depends on factors including earnings and the applicable rules for the tax year.
Don’t assume that because you’ve paid Income Tax, National Insurance is included inside that same number.
They are separate.
## 8. Check Your Workplace Pension Contribution
If you’re enrolled in a workplace pension, your payslip may also show a pension deduction.
It might appear under wording such as:
Pension
Employee pension
Workplace pension
Pension contribution
The way pension contributions appear can depend on how your employer’s pension arrangement operates.
For example, workplace pension contributions can be handled through different arrangements, including **net pay** and **relief at source**, which can affect how the contribution and tax relief appear.
If you don’t understand the pension deduction, ask your employer or pension provider what type of arrangement is being used.
Don’t assume money deducted for your pension is simply another tax.
It may be money being contributed toward your retirement.
## 9. Student Loan or Postgraduate Loan Deductions
Some employees may also have deductions for:
Student Loan repayments
Postgraduate Loan repayments
Whether these deductions apply depends on your circumstances and applicable repayment rules.
If you don’t have the relevant loan, you wouldn’t normally expect such a deduction.
If an unfamiliar student-loan deduction suddenly appears, investigate rather than ignoring it.
## 10. Look for Other Deductions
Your payslip can contain deductions beyond tax, National Insurance, and pension contributions.
Depending on your employer and circumstances, these might include things such as:
Workplace benefits
Salary-related arrangements
Union subscriptions
Repayment of an employer loan
Attachment or other authorised deductions
Other agreed deductions
The exact wording varies.
If you see a deduction you don’t recognize, ask payroll or HR what it represents.
Even a relatively small deduction matters when it repeats every month.
For example:
**£40 per month × 12 months = £480 per year.**
Understanding every recurring deduction is therefore worth a few minutes of your time.
## 11. Find Your Net Pay
Now we reach the number most employees immediately look for:
**Net pay.**
Net pay is generally the amount remaining after the applicable deductions have been taken from your gross earnings.
Consider a simplified hypothetical example:
Gross pay: **£2,800**
Income Tax: **£300**
National Insurance: **£140**
Pension contribution: **£120**
Other deductions: **£40**
Total deductions:
**£600**
Estimated net pay:
**£2,200**
This example is purely illustrative and is not a tax calculation for a specific employee.
Your actual net pay depends on your earnings, tax code, pension arrangements, National Insurance position and other deductions.
## 12. Gross Pay and Net Pay Are Not the Same Thing
This distinction is essential when comparing jobs.
Suppose an employer offers:
**£36,000 per year**
That doesn’t mean you’ll receive:
**£3,000 in your bank account every month.**
£36,000 divided by 12 gives £3,000 of average monthly **gross salary**, assuming a simple evenly paid annual salary.
But deductions still need to be considered.
The amount reaching your bank account can be lower after Income Tax, National Insurance, pension contributions, and any other deductions.
This is why someone planning rent, a car payment, or monthly savings should budget around expected **take-home pay**, not simply gross salary.
## 13. Check “Year to Date” Figures
Many payslips contain a section called:
**YTD**
or:
**Year to Date**
This can show cumulative figures for the current tax year.
Depending on the payslip, you might see totals for:
Gross taxable pay
Income Tax
National Insurance
Pension contributions
Other amounts
These numbers can help you understand how much you’ve earned and how much has been deducted over the year rather than looking at only one month.
Suppose your monthly tax looks unusual.
Checking the year-to-date figures can give you additional context.
## 14. Why Did My Take-Home Pay Change This Month?
This is a common question.
Your net pay can change even if your hourly rate or annual salary hasn’t changed.
Possible reasons include:
You worked more or fewer hours.
You received overtime.
You received a bonus.
Your tax code changed.
Your pension contribution changed.
Another payroll deduction started or stopped.
Your taxable pay changed.
National Insurance deductions changed because of earnings.
You had holiday, sick, maternity, paternity or another type of statutory or employer payment.
Don’t immediately assume that a lower paycheck means payroll made a mistake.
Compare the current payslip with the previous one line by line.
Usually, you’ll be able to identify what changed.
## 15. Starting a New Job? Pay Extra Attention to Your Tax Code
The first few payslips after starting a new job deserve extra attention.
Your new employer normally uses information such as your **P45** when setting up payroll.
If the employer doesn’t have the information needed, another tax code or an emergency basis may initially be used.
That can affect the amount deducted.
So if your first paycheck is significantly lower than expected, don’t look only at your gross pay.
Check your tax code.
If something doesn’t look right, compare the code on your payslip with the information HMRC holds for you.
## 16. Working Two Jobs? Don’t Assume Both Payslips Should Look the Same
This is especially important for people working multiple jobs.
Your tax arrangements can differ between jobs.
Your Personal Allowance isn’t simply duplicated for every job you have.
As a result, the tax code on your second job may look different from the one on your main employment.
For example, some people may see a **BR** code on an additional source of income, depending on their circumstances.
This doesn’t automatically mean payroll made a mistake.
But you should verify that HMRC has accurate information about your jobs and expected income.
## 17. Overtime Can Make the Payslip Look Very Different
Imagine your normal monthly gross pay is:
**£2,500**
But this month you work substantial overtime and gross pay increases to:
**£3,200**
Your deductions may also increase.
Some workers see the larger deduction and think:
“Working overtime wasn’t worth it because tax took everything.”
That conclusion can be misleading.
Income Tax operates using tax bands and payroll calculations. Moving into a higher tax band does not normally mean every pound of your entire income suddenly becomes taxed at the higher rate.
Look at the additional **net income**, not only the fact that the tax deduction increased.
## 18. Keep Your Payslips
Don’t delete your digital payslips immediately after checking your bank account.
Payslips can be useful evidence of:
Your earnings
Taxes paid
Pension contributions
Employment income
They can also help when you’re trying to understand an old payroll issue.
Depending on your circumstances, proof of income can be useful when dealing with financial applications or other administrative matters.
Keeping organised copies can save considerable time later.
## 19. What Should You Do If Something Looks Wrong?
Start by identifying the exact issue.
Is your gross pay incorrect?
Are hours missing?
Is the overtime rate different from what you expected?
Is there an unfamiliar deduction?
Has your tax code changed?
Is your pension contribution different?
If the problem appears related to hours, salary, overtime, or another employer-controlled payroll item, contact your employer’s payroll or HR department.
If the concern relates to your tax code, check what HMRC currently has on record.
Don’t ignore a possible error for months.
A small monthly discrepancy can become a much larger amount over a year.
## A Simple Payslip Checklist
Every time you receive your salary, take a minute to check:
**Pay period** — Is this the correct month or week?
**Hours worked** — Do they match what you expected?
**Gross pay** — Does your salary, hourly pay and overtime look correct?
**Tax code** — Has it changed?
**Income Tax** — How much PAYE tax was deducted?
**National Insurance** — How much NI was deducted?
**Pension** — Is your expected contribution shown?
**Other deductions** — Do you recognize every one?
**Net pay** — Does it match what reaches your bank account?
**Year-to-date totals** — Do the cumulative figures look reasonable?
You don’t need to be an accountant.
You simply need to understand what each major number means.
## The Bottom Line
If you’re an Albanian working in England, don’t look only at the final amount deposited into your bank account.
Your payslip tells the story of how you went from:
**Gross Pay → Income Tax → National Insurance → Pension/Other Deductions → Net Pay**
Understanding that journey can help you spot payroll mistakes, understand why your take-home pay changed, check your tax code, monitor pension contributions, and create a more realistic monthly budget.
Pay particular attention when you:
**Start a new job**
**Take a second job**
**Begin working overtime**
**Receive a bonus**
**See your tax code change**
**Join or change a workplace pension**
**Notice an unexpected deduction**
The final number on your payslip matters—but understanding **why that number is what it is** matters just as much.
*Disclaimer: This article provides general educational information and does not constitute personalised tax, financial, pension, employment or legal advice. UK tax, National Insurance, pension and payroll rules can change, and individual circumstances vary. Check your current information with HMRC, your employer, pension provider or an appropriately qualified professional when necessary.*