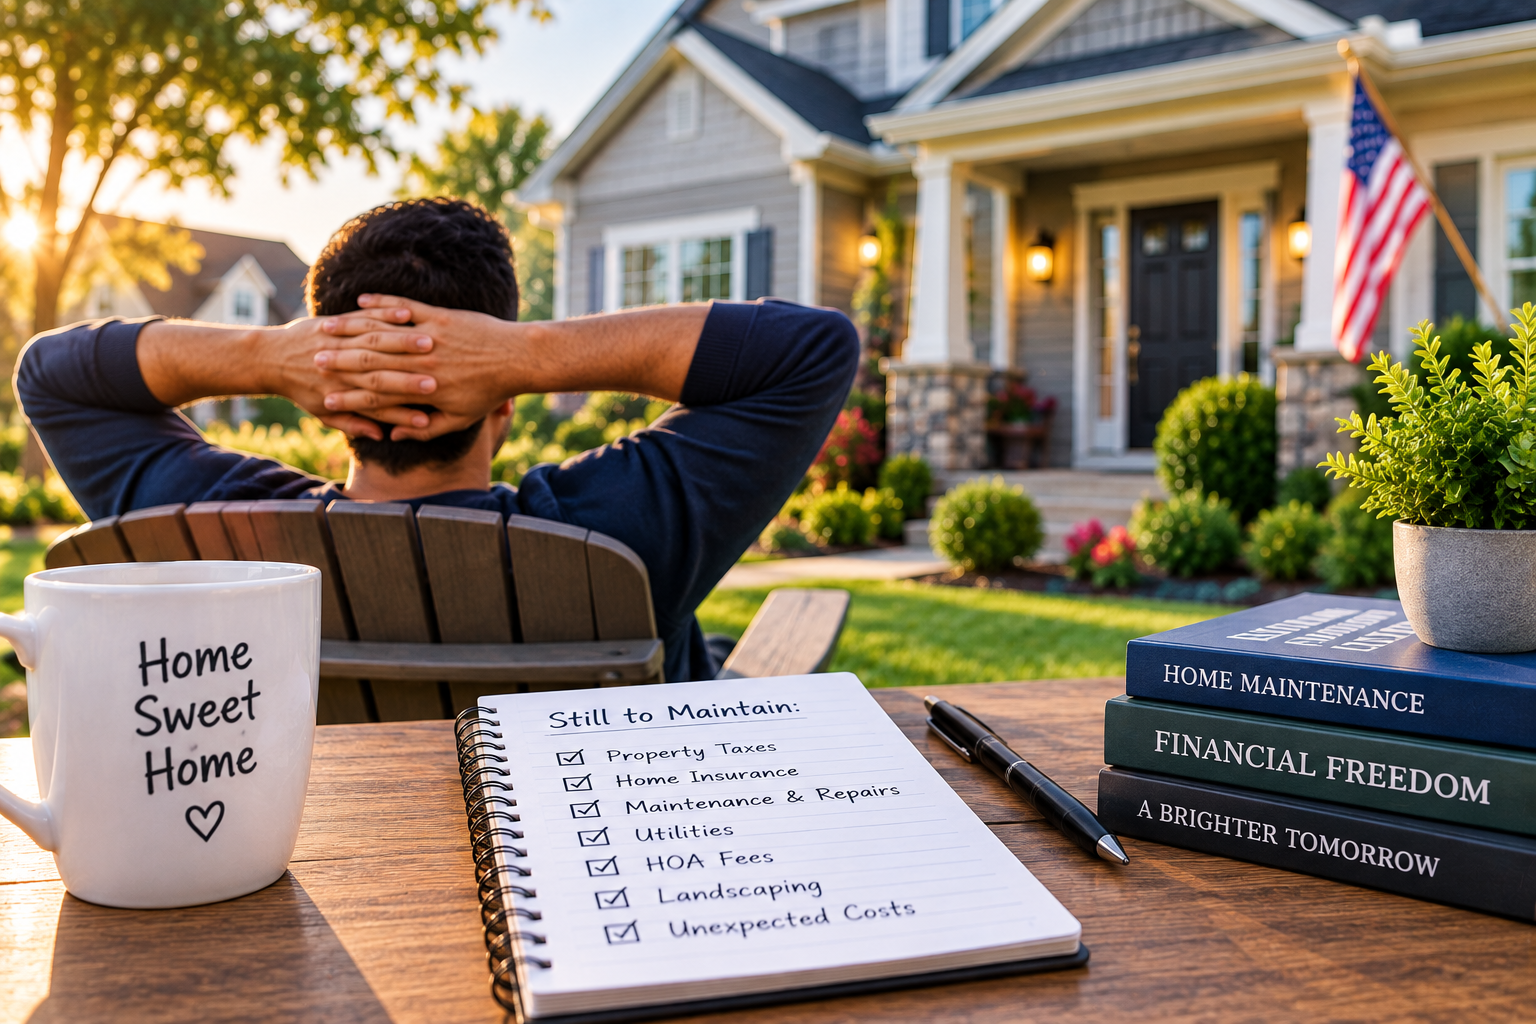
Paid Off Your Home? These Expenses Don’t Disappear With the Mortgage
After 15, 20 or 30 years of payments, you finally make the last mortgage payment.
The house is paid off.
For many families in America, this is one of the biggest financial milestones of their lives.
No more principal.
No more mortgage interest.
No more monthly loan payment.
But there’s an important reality homeowners should understand:
A paid-off house is not a free house.
Even after the mortgage disappears, several major expenses can continue for as long as you own the property.
For Albanians living in America who are approaching retirement or have already paid off their homes, understanding these expenses can make the difference between a realistic retirement budget and an unpleasant financial surprise.
Mortgage-Free Doesn’t Mean Housing-Cost-Free
A traditional mortgage payment can contain several components.
The CFPB commonly describes them as:
Principal
Interest
Taxes
Insurance
Principal and interest are connected directly to the mortgage loan.
Property taxes and homeowners insurance are different.
They’re costs associated with owning the property. CFPB specifically notes that property taxes and homeowners insurance generally remain costs of homeownership whether or not you have a mortgage.
Once the loan is paid off:
Principal → disappears
Mortgage interest → disappears
But many other expenses remain.
Let’s look at them.
1. Property Taxes Don’t Disappear
This is one of the most important expenses to remember.
Paying off your mortgage does not eliminate:
Property taxes.
Suppose your house is fully paid off and worth:
$500,000.
Your annual property-tax bill might hypothetically be:
$7,200
That equals:
$600 per month
or:
$7,200 every year.
Your actual tax bill could be much lower or much higher depending on your state, county, municipality, assessed value, exemptions and local tax rules.
But the key point remains:
Owning 100% of the house doesn’t eliminate the government’s property-tax bill.
Think of Property Tax as a Monthly Expense
Even if you pay it once or twice per year, divide the annual amount by 12.
If property tax is:
$9,600/year
your effective monthly cost is:
$800.
This makes your budget more realistic.
Your Escrow Account May Disappear
While you have a mortgage, your servicer may collect money every month for:
Property taxes
Homeowners insurance
Those funds are often held in an:
Escrow account.
The servicer then pays the bills when they’re due.
After the mortgage is fully paid, that arrangement normally ends because there is no longer a mortgage servicer collecting your monthly payment.
That means you may become directly responsible for managing those bills yourself.
Instead of sending:
$2,500 every month
to one mortgage company, you may now need to remember:
Property-tax deadlines
Insurance renewal dates
Other property bills
Don’t mistake the disappearance of escrow for the disappearance of the expense.
2. Homeowners Insurance Still Matters
Once the mortgage is gone, your lender no longer has the same reason to require homeowners insurance.
But that doesn’t mean the financial risk disappears.
Imagine you’ve spent decades paying for a house that’s now worth:
$500,000.
Then a major covered disaster causes severe damage.
Without appropriate insurance, you could potentially be responsible for an enormous loss yourself.
Homeowners insurance can provide protection for the structure, belongings, liability and other covered losses according to the policy’s terms.
The exact coverage, exclusions, deductibles and limits vary by policy.
Example
Suppose your annual premium is:
$2,400
Equivalent monthly cost:
$200
Mortgage:
$0
Insurance:
Still $200/month
And premiums can change over time.
A paid-off home can still be one of the largest assets your family owns.
Protecting it remains an important financial consideration.
3. Repairs Never Stop
Your bank doesn’t care if your roof is 25 years old once the mortgage is paid off.
But your roof does.
Homeownership means maintaining physical systems that age over time:
Roof
HVAC
Plumbing
Electrical systems
Water heater
Windows
Doors
Foundation
Sewer or septic systems
Appliances
Exterior
Driveway
Deck
Drainage
A paid-off mortgage doesn’t stop these components from getting older.
The CFPB specifically recommends budgeting for maintenance and repairs as ongoing costs of homeownership.
One Repair Can Equal Months of “Saved Mortgage Payments”
Imagine your mortgage used to cost:
$2,000/month.
You pay it off.
You’re excited because you’ve freed:
$24,000 per year.
Then during the next few years you face hypothetical expenses such as:
Roof work: $12,000
HVAC replacement: $8,000
Water heater: $1,800
Plumbing repair: $2,500
Electrical work: $2,000
Total:
$26,300
These figures are illustrative, not national price estimates.
The point is that home repairs don’t stop because the loan balance reaches zero.
Build a Home-Repair Fund
Instead of assuming:
“No mortgage means I can spend the entire old payment,”
consider redirecting part of that money into a home reserve.
For example:
$300/month
becomes:
$3,600/year
After five years, before withdrawals:
$18,000
Or:
$500/month
becomes:
$6,000/year
After five years:
$30,000
There’s no universal amount every homeowner should save.
A newer small home and an older large home can have completely different maintenance requirements.
But having cash available can reduce the need to put a major repair on a high-interest credit card.
4. Utilities Continue Every Month
Mortgage paid:
Yes.
Electricity paid forever:
No.
You’ll still need to budget for expenses such as:
Electricity
Natural gas
Water
Sewer
Trash collection
Internet
Other local utilities
The IRS itself treats utilities, repairs, property insurance and property taxes as separate costs associated with maintaining a home.
Example
Suppose a household spends:
Electricity: $180
Gas: $100
Water/sewer: $90
Trash: $35
Internet: $80
Total:
$485/month
Annualized:
$5,820
Again, these are hypothetical figures.
But they illustrate why a household with no mortgage can still have substantial monthly housing costs.
5. HOA Fees Don’t Disappear Either
If your home is part of a:
Homeowners Association (HOA)
you may continue paying HOA dues after the mortgage is gone.
The mortgage and HOA are separate obligations.
CFPB explains that HOA or condo dues are generally paid separately from the mortgage and can range from hundreds to more than a thousand dollars per month depending on the property.
Suppose your HOA costs:
$300/month
That’s:
$3,600/year.
Over 10 years, assuming no change:
$36,000.
And HOA dues can increase.
Depending on the association, owners may also face special assessments for major community expenses.
6. Landscaping and Exterior Maintenance Continue
If you own a detached home, someone still needs to handle:
Grass
Trees
Snow
Gutters
Exterior cleaning
Pest control
Driveway
Fence
Landscaping
You may do the work yourself.
Or you may pay someone else.
Either way, there can be costs.
This becomes particularly important as homeowners get older.
A 45-year-old homeowner may personally handle many maintenance tasks.
At 75, they may prefer or need to hire contractors.
Retirement planning should consider that possibility.
7. Major Replacements Are Inevitable Over Long Periods
Some home expenses don’t happen monthly.
That’s exactly why people forget about them.
You don’t buy a new roof every month.
You don’t replace an HVAC system every year.
But eventually large components may need repair or replacement.
Imagine setting aside nothing for:
10 years
because:
“The house is paid off.”
Then several major systems reach the end of their useful life around the same period.
Suddenly the household may need thousands of dollars.
A sinking fund can make irregular costs more manageable.
Instead of treating a future roof replacement as completely unexpected, you gradually reserve money for major home expenses.
8. Insurance Beyond Standard Homeowners Coverage May Still Be Relevant
Standard homeowners insurance doesn’t necessarily protect against every risk.
Depending on where the property is located, homeowners may need or consider additional coverage, such as:
Flood insurance
Earthquake insurance
Other supplementary coverage
CFPB specifically advises homeowners to consider supplementary insurance and notes that flood-risk areas may require or justify additional flood coverage.
The right insurance structure depends heavily on the property and location.
A paid-off mortgage doesn’t make the house immune to disasters.
9. Renovations and Accessibility Can Become Important Later
A house that works perfectly when you’re 50 may not work as well when you’re 75.
Future projects could include:
Bathroom renovations
Roof replacement
New flooring
Kitchen work
Windows
Insulation
HVAC improvements
Accessibility modifications
Stairs or railings
Exterior repairs
Some are optional.
Others can become necessary.
This is particularly relevant for homeowners who plan to:
Age in place.
If the house is intended to be your retirement home, think about what maintaining and adapting it could cost over the next 20 or 30 years.
The Paid-Off $500,000 House Example
Imagine an Albanian couple owns a home worth:
$500,000
Mortgage balance:
$0
They proudly say:
“Our housing cost is zero.”
But let’s calculate a hypothetical annual budget.
Property taxes: $7,200/year
Homeowners insurance: $2,400/year
Utilities: $5,400/year
HOA: $2,400/year
Maintenance reserve: $4,800/year
Landscaping/pest/exterior: $1,800/year
Total:
$24,000/year
Equivalent:
$2,000/month
The mortgage is completely gone.
Yet the home could still consume roughly:
$24,000 annually
under these hypothetical assumptions.
That doesn’t mean every paid-off home costs $24,000 annually.
Some will cost far less.
Others can cost substantially more.
The example simply demonstrates:
Paid off does not mean free.
Compare Before and After the Mortgage
Imagine the household previously paid:
Principal + interest: $2,200
Taxes: $600
Insurance: $200
Total mortgage-related payment:
$3,000/month
After the mortgage is gone:
Principal + interest: $0
But:
Property taxes: $600
Insurance: $200
The household immediately frees:
$2,200/month
not necessarily the entire:
$3,000.
And it still needs to account for:
Maintenance
Utilities
HOA
Repairs
Other ownership expenses
That’s the number homeowners should use when planning retirement.
What Happens to the Money You Used to Send to the Bank?
This is where paying off a house can become financially powerful.
Suppose your former principal-and-interest payment was:
$1,800/month
That’s:
$21,600/year
Once the mortgage is gone, you can potentially redirect some of that cash flow toward other goals.
For example:
Emergency savings
Retirement
Home repairs
Healthcare
Travel
Investments
Helping family
Other financial goals
The important part is not allowing the entire former mortgage payment to disappear automatically into lifestyle spending.
A Paid-Off House Can Still Create Financial Stress
Imagine a retired couple has:
House value: $600,000
Mortgage:
$0
But monthly retirement income is:
$3,500.
Now suppose housing-related costs average:
Property taxes: $700
Insurance: $250
Utilities: $450
HOA: $200
Maintenance reserve: $300
Total:
$1,900/month
That would represent more than half of their:
$3,500 monthly income.
They may be wealthy on paper because they own a valuable home.
But their monthly cash flow could still be tight.
This is sometimes described as being:
House-rich but cash-poor.
The value of the property and the money available to pay monthly bills are two different things.
Property Taxes Matter Especially in Retirement
Suppose you bought your home decades ago.
Your mortgage eventually disappears.
But property taxes can remain and may change over time.
Some states or local jurisdictions offer programs such as:
Senior exemptions
Homestead exemptions
Property-tax relief
Deferrals
Other programs
Eligibility and rules vary widely.
If you’re approaching retirement, check directly with your local taxing authority to see what programs actually exist where you live.
Don’t assume your property taxes automatically disappear at a certain age.
Don’t Assume Every Home Expense Is Tax-Deductible
Another misconception is:
“I own a home, so I can deduct all these expenses.”
That’s not generally true.
For a personal residence, expenses such as homeowners insurance, utilities and many ordinary household costs generally aren’t deductible as personal homeownership expenses.
The IRS notes that taxpayers generally need to itemize to claim qualifying homeownership deductions and distinguishes deductible real-estate taxes or qualifying mortgage interest from costs such as homeowners insurance and utilities.
Tax rules change and individual situations differ, so don’t make financial decisions based solely on an assumed deduction.
Make Sure the Mortgage Is Actually Paid Off
If you’re planning to pay the mortgage off early, don’t simply look at the balance displayed online and send that exact amount.
Your:
Current balance
and:
Payoff amount
can be different.
CFPB explains that the payoff amount can include interest through the payoff date and potentially other outstanding charges; borrowers can request an accurate payoff statement from their servicer.
Once the loan has been satisfied, keep the relevant records confirming the payoff.
Your New “Mortgage Payment” Could Be to Yourself
Here’s a useful way to think about life after the mortgage.
Suppose your old mortgage payment was:
$2,500/month.
Instead of suddenly treating all $2,500 as spending money, you might create your own monthly allocation.
For example:
Home maintenance reserve: $400
Property-tax reserve: $600
Insurance reserve: $200
Long-term savings/investments: $800
Additional retirement/emergency savings: $500
Total:
$2,500
The bank no longer receives the payment.
But you’re still intentionally assigning the money.
That’s how eliminating a mortgage can improve long-term financial security instead of simply increasing lifestyle spending.
Calculate Your Real Mortgage-Free Housing Cost
Take your annual:
Property taxes
plus:
Homeowners insurance
HOA
Average utilities
Routine maintenance
Expected major repairs
Landscaping
Other recurring property expenses
Then divide annual costs by:
12
For example:
Taxes: $7,200
Insurance: $2,400
HOA: $2,400
Utilities: $5,400
Maintenance/repair reserve: $4,800
Other costs: $1,800
Annual total:
$24,000
Monthly equivalent:
$2,000
Now you know your approximate:
Mortgage-free housing budget.
That’s far more useful than simply saying:
“My house is paid off.”
The Bottom Line
Paying off your mortgage is a major financial achievement.
It can eliminate:
Principal payments
and:
Mortgage interest payments.
But it does not eliminate the cost of owning a home.
You’ll generally still need to plan for expenses such as:
Property taxes
Homeowners insurance
Utilities
Repairs and maintenance
HOA dues, if applicable
Landscaping and exterior upkeep
Major future replacements
Additional insurance where appropriate
CFPB explicitly distinguishes property taxes and homeowners insurance as costs of homeownership rather than costs of borrowing money—meaning you would generally face them with or without a mortgage.
For Albanians in America who have paid off their homes or are approaching the final mortgage payment, don’t build your future budget around:
“My housing cost will become $0.”
Instead ask:
“What will this house cost me every year after the bank is gone?”
A paid-off home can dramatically reduce monthly expenses and provide substantial financial security.
But:
Mortgage-free doesn’t mean expense-free.
The loan eventually ends.
Homeownership continues.
Disclaimer: This article is for general educational purposes only and does not constitute personalised financial, tax, legal, insurance, retirement or investment advice. Property taxes, insurance, HOA fees, utilities and maintenance costs vary significantly by location and property. All dollar examples are hypothetical.